Vivid Money Review 2026: Business Banking with Cashback, Tested
Fastlancer Team · Updated: Oct 20, 2026
Short verdict
Ideal for
- Freelancers in Germany and the EU who want a free account with a German IBAN
- Self-employed people with high card spend who want cashback on it
- Founders who need sub-accounts with their own IBANs for reserves and projects
- App-first users who never need cash deposits or a branch
Not ideal for
- Anyone who needs to deposit cash
- Businesses that depend on full deposit protection
- People who need an overdraft
- Entry price
- Free plan · paid from €6.90 / month
- Free to start?
- Yes — Standard plan free forever; paid plans come with 2 free months
- Stands out for
- Free business account with a German IBAN, cashback on card spend, interest on balances and built-in invoicing — the app bank for self-employed people who want their account to work for them
What is Vivid?
Vivid Money is a fintech with its own e-money licence (CSSF, Luxembourg) that positions its business account squarely on price and perks: a free-forever entry plan, cashback on card spend, interest on balances and a built-in invoicing tool. Practically every legal form is accepted — from sole traders to a GmbH in formation — and freelancers get their own plan line — same prices as the company line, but with higher interest, a bigger cash allowance and unlimited receipt uploads.
That places Vivid in the gap between bare-bones free fintechs and tax-focused specialists like Finom or Kontist: more perks than a plain free account, less tax automation than the specialists.
Cashback and interest: the account as a yield product
The number-one selling point is interest on business balances — 4% p.a. as a promo for the first 4 months, then 0.5% (Standard), 2.5% (Prime), 2.6% (Pro) and 2.7% (Pro+) on up to €30,000 (USD/GBP balances earn slightly less on Prime and Pro). On Standard the promo rate only applies up to €5,000. Add cashback on business card spend: 0.1% base on the free plan, more on paid plans, with up to 6% category cashback on Pro. The honest math: if four figures a month run through your company card (ads, SaaS, travel), the plan fee pays for itself (category cashback is capped at €150 a month) — with little card spend, stay on the Standard plan.
Sub-accounts, invoicing, accounting
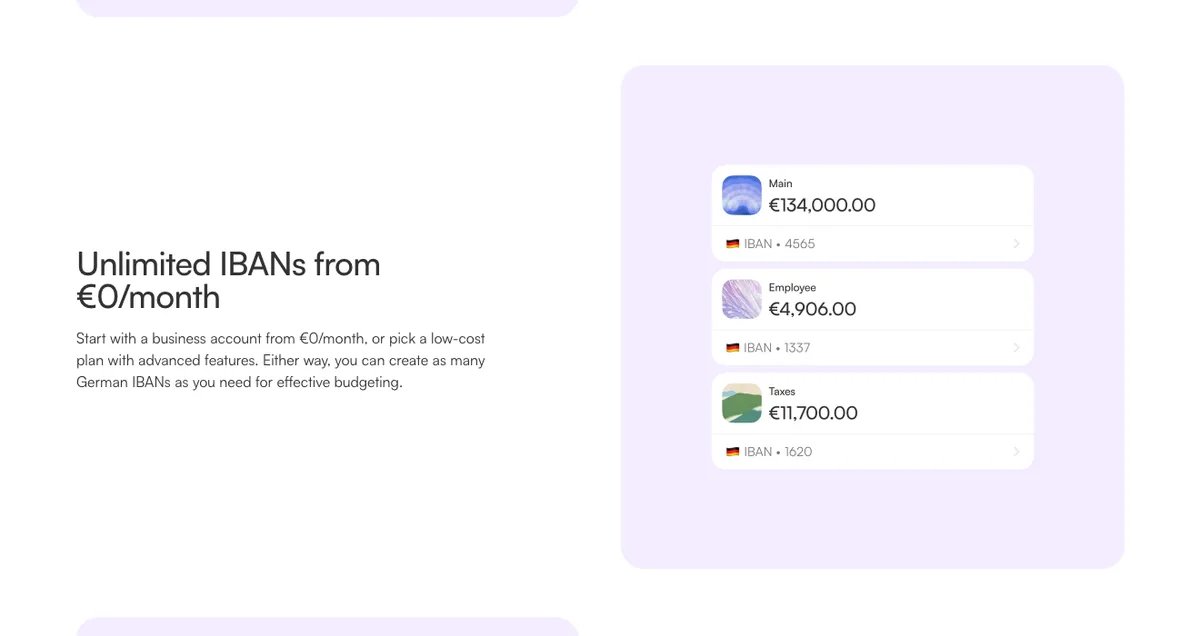
Sub-accounts with their own German IBANs organise tax reserves, fixed costs and projects — from Prime, foreign-currency accounts in 20+ currencies come on top for international clients (Standard: EUR only). An invoicing tool is included free on every plan; receipts can be uploaded without limit on every plan and handed to your accountant via DATEV or Lexware Office exports — on the free Standard plan too. There is no automatic tax-reserve calculation like Kontist offers.
The catch: e-money, not a bank
Since 2024 Vivid no longer partners with Solaris — it safeguards funds itself as an e-money institution, separated from company assets with only the share held at partner bank Natixis covered by the French deposit guarantee up to €100,000 — money-market fund units are not. Add the typical fintech constraints: no cash deposits, no overdraft, digital-only support (24-hour chat). Vivid scores 4.7/5 on Trustpilot from almost 30,000 reviews, but the most serious recurring complaint is sudden account freezes with slow resolution — a real operational risk for a business account, best hedged with a second account elsewhere.
Who is Vivid worth it for?
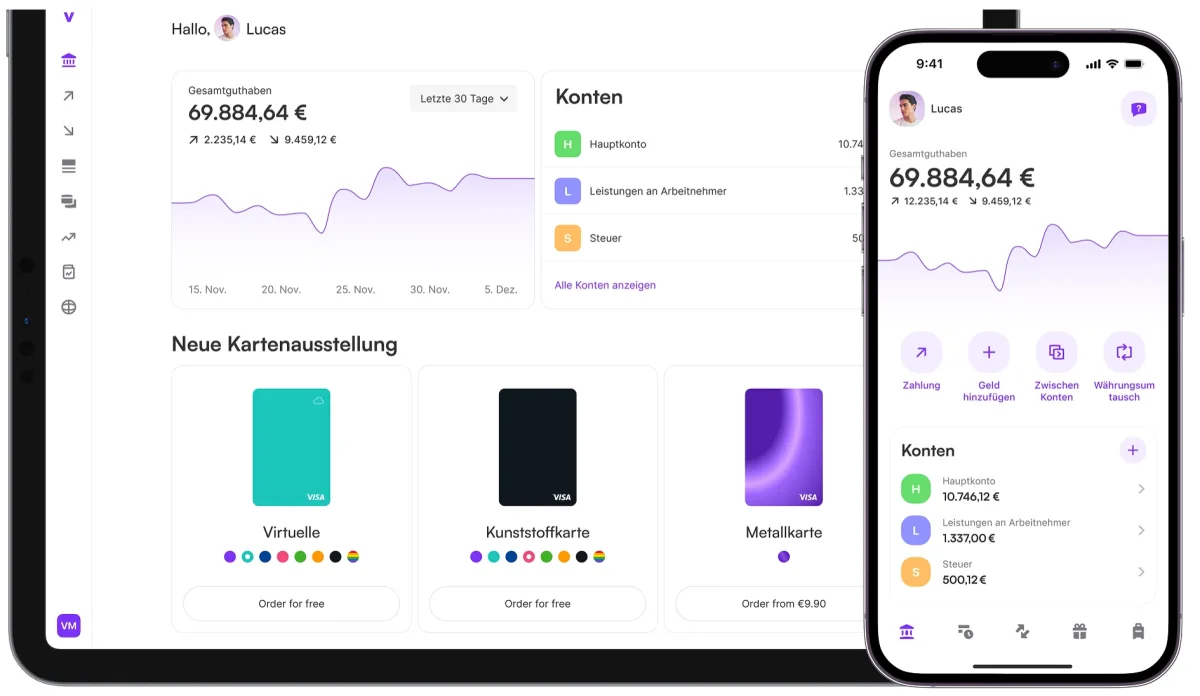
Vivid fits digital-first self-employed people who want a free or cheap account with a German IBAN and already run their spending through cards — then cashback and interest stack into a real price advantage. If you need automatic tax reserves, cash handling or full-bank deposit protection, look at Kontist or a classic bank — we compare the whole market in our business account overview.
What we like about Vivid and what we don't
Pros
- Free plan with German IBAN
- Cashback up to 6% on Pro
- Interest on account balances
- Free invoicing tool included
- Sub-accounts with own IBANs
Cons
- E-money institution, limited deposit protection
- Account freezes reported, slow support
- No cash deposits or overdraft
Pricing
Standard
Free
free forever (freelancer plan line)
- German IBAN, free SEPA transfers
- 0.1% base cashback
- Invoicing tool included
Prime
6,90 €
per month billed yearly (€8.90 monthly) — first 2 months free
- Higher cashback (up to 4% in categories)
- Foreign-currency accounts in 20+ currencies (Standard: EUR only)
- Better interest on balances
Pro
18,90 €
per month billed yearly (€24.90 monthly) — first 2 months free
- Up to 6% cashback (Pro)
- 2.6% interest after the promo phase (up to €30,000)
- Higher free allowances: €1,500 cash, 10 SWIFT transfers, €30,000 FX
Pro+
41 €
per month billed yearly (€50 monthly) — first 2 months free
- Up to 8% cashback in categories, 0.75% guaranteed
- 15 free outgoing SWIFT transfers per month
- For full-time, high-revenue freelancers
Prices may change — check the official website for current plans.
Price history
Checked Oct 20, 2026 · 3 plans unchanged since Oct 20, 2026
Alternatives by use case
Frequently Asked Questions
How much does the Vivid business account cost?
Three plans for the self-employed, with a permanently free entry; annual billing is cheaper than monthly. The paid tiers differ mainly in cashback, sub-accounts with their own IBANs and foreign spending. Worth knowing regardless of price: Vivid is an e-money institution, not a bank, so deposit protection works differently.
How does Vivid cashback work?
Vivid pays cashback on business card spend, tiered by plan: 0.1% base on the free plan, more on paid plans — the advertised "up to 6%" applies to category cashback on the Pro plan, not every transaction. If you run ads, software and travel through the company card, cashback can cover the plan fee; with little card spend the effect stays small.
Is my money safe with Vivid?
Differently from a classic bank: Vivid Money S.A. is an e-money institution licensed by Luxembourg's CSSF — your balance sits separately from company assets in client-money accounts at partner banks and in money-market funds. According to Vivid, the share held at the French bank Natixis is covered by the French deposit guarantee scheme FGDR up to €100,000 per client; the fund units are not. That's regulated and normal for fintechs, but a different protection level than a full bank — worth knowing if you park large reserves.
Does Vivid come with a German IBAN?
Yes — every plan comes with a German IBAN, and sub-accounts each get their own DE IBAN too. The old fintech problem of foreign IBANs being rejected for direct debits doesn't apply here. You also get USD and GBP accounts for international clients.
Vivid or Kontist/bunq — which fits better?
Vivid wins on cost and extras: free plan, cashback, interest, invoicing. Kontist counters with automatic tax reserves, bunq with tiered sub-accounts and sustainability features. Rule of thumb: maximum cost efficiency and cashback = Vivid; automatic tax organisation = Kontist.
Verdict
Vivid is the value play among business accounts: use the free plan or activate cashback with your card spend and you get a lot of account for very little money — German IBAN, sub-accounts, interest and invoicing included. The price is the fintech setup: an e-money licence with only partial deposit protection, no cash, digital-only support — and the account-freeze complaints on Trustpilot are worth knowing. Strong as a low-cost account for digital-first self-employed people; for parking large reserves we'd still want a full bank.