Tide Review 2026: Business Account Plans, Fees and the FSCS Question
Fastlancer Team · Updated: Sep 2, 2026
Short verdict
Ideal for
- UK sole traders and limited company directors who want an account open the same day
- Freelancers making a handful of payments a month, where Free genuinely stays free
- Anyone spending abroad — paid plans drop the 2.75% FX fee to zero
- Businesses holding a cash balance: the savings rate rises with the plan
Not ideal for
- Anyone without a UK address or UK-registered company
- Freelancers needing a euro account or EU IBAN
- Businesses making more than five transfers a month on Free
- Entry price
- Free plan · paid from €1,249 / month
- Free to start?
- Not needed — the Free plan has no monthly fee
- Stands out for
- A UK business account you can open from the app in minutes, with no hard credit check and no monthly fee on the entry plan.
What Tide is
Tide is a UK business account you open from an app rather than a branch: no appointment, no hard credit check, minutes rather than days. It serves sole traders and limited companies, and by its own count more than two million of them. The entry plan carries no monthly fee, which is the reason most people arrive.
What you get on top of the account is the part that distinguishes it from a plain current account — invoicing, Making Tax Digital tools, savings pots including a dedicated Tax Saver, card readers, and accounting connectors. It is built as the finance layer for a small business, not just somewhere to keep money.
Tide plans and pricing 2026
Four plans, all billable monthly or annually. The differences are mostly about volume and about how much of the admin layer is included.
Read down the Free column and one number does all the work. Five bank transfers a month is the real boundary of the free plan — not a fee, a ceiling. Pay four suppliers and your accountant and you have used it. Everything else on Free is usable: the card, direct debits, ATM withdrawals, cash and cheque deposits at the Post Office or a PayPoint, Making Tax Digital tools, and a savings account paying 2% AER.
One oddity worth flagging: invoicing stays capped at three a month all the way through Pro. You pay £27.49 and still get the same three invoices as someone paying nothing. Only Max lifts it. If invoicing volume is your bottleneck, Tide's plans are not the lever — a separate invoicing tool is cheaper than the jump to £69.99.
When a paid plan pays for itself
Two honest calculations, because the marketing points at the wrong one.
The FX fee is the strongest case. Free charges 2.75% on international card payments; every paid plan charges nothing. Spend £455 a month abroad — a couple of SaaS subscriptions and a flight — and Smart has already paid for itself at £12.49.
The savings rate is the weakest case, despite being the most visible difference in the table. Pro pays 3% AER against Free's 2%, a single point. Pro costs £329.88 a year, so on interest alone you need roughly £33,000 parked in the Instant Saver before the plan breaks even. For Max at £839.88 a year against Free, the figure is around £67,000. Buy the plan for transfers and FX; treat the better rate as a bonus, not a reason.
The part most reviews skip: is your money protected?
Tide says it in its own footer, and it deserves to be read: "Tide is not a bank." It is an electronic money institution authorised by the FCA under reference 900843. That is not a warning in itself — it is how most modern business accounts work — but it changes where your deposit protection comes from.
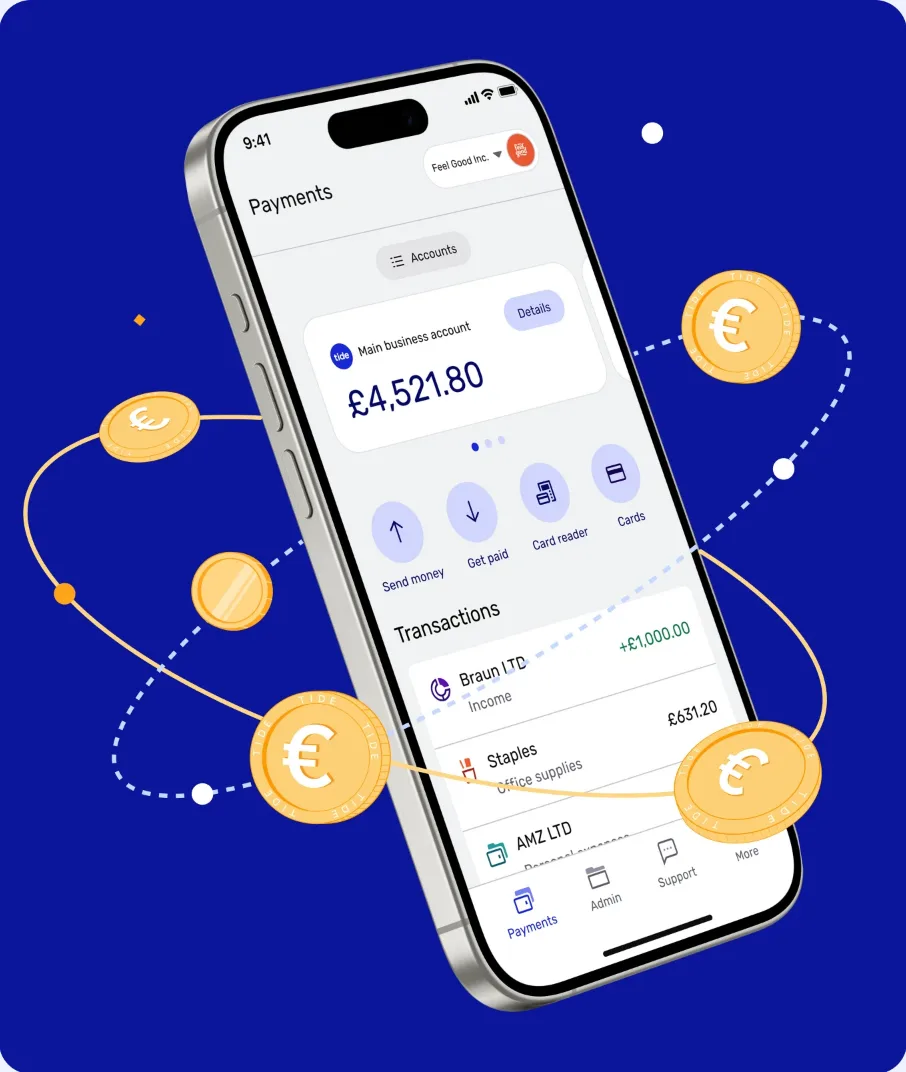
- 04-06-05 — the account is provided by ClearBank, and eligible deposits are covered by the FSCS up to £120,000
- 23-69-72 — the account is an e-money account from PrePay Technologies, which is not FSCS-covered; the funds are safeguarded, protecting you if PPT becomes insolvent, but that is not the deposit guarantee scheme
New accounts are ClearBank-powered, so most readers opening one today land in the first group. The distinction matters if you hold a meaningful balance, and it matters twice if you also bank elsewhere with ClearBank — the £120,000 is aggregated across everything you hold with them, not per account.
What customers actually complain about
Tide's public record is good: 4.4 out of 5 across nearly 38,000 Trustpilot reviews, with praise concentrated on how fast onboarding is and how helpful support is once you reach it. The company replies to 99% of negative reviews, usually within a day.
The recurring complaints are worth knowing before you move your main account across. Frozen accounts during compliance checks come up repeatedly — funds temporarily inaccessible while checks run, which for a business mid-payroll is not a small inconvenience. Alongside that: slow responses on urgent issues, declined applications without a clear reason, and heavy sales contact about add-on products after signup. None of that is unique to Tide among app-first providers, but it is the risk you take on with any of them.
Who can actually open one
This is the question that decides it for a lot of readers. Tide requires a UK residential address and phone number. If you are based elsewhere, you can still apply — but only as a director of a company registered with UK Companies House, and additional checks may follow. There is no German IBAN and no euro business account.
What we like about Tide and what we don't
Pros
- No monthly fee, no hard credit check
- Paid plans remove the 2.75% FX fee
- Savings rate climbs from 2% to 3.25%
- Trustpilot score of 4.4 across 38,000 reviews
Cons
- Only five transfers a month on Free
- Tide is not a bank
- Account freezes during compliance checks
Pricing
Free
Free
no monthly plan fee
- 5 bank transfers a month
- 2.75% FX fee on international card payments
- 3 invoices a month, Making Tax Digital tools
Smart
£12.49
per month
- 30 transfers a month, 0% FX fees
- 1 extra business account, 1 team card
- Xero connector and a business phone number
Pro
£27.49
per month
- Unlimited transfers, 0% FX fees
- 2 extra accounts, 2 team cards, 2 CHAPS payments
- Tide Accounting included
Max
£69.99
per month
- 0.5% cashback and unlimited invoicing
- 3 extra accounts, 3 team cards, 5 CHAPS payments
- Payroll software and credit score insights
Prices may change — check the official website for current plans.
Price history
Checked Oct 16, 2026 · 3 plans unchanged since Sep 14, 2026
Alternatives by use case
- Finom If the business is in the EU and needs a local IBAN
- bunq If sub-accounts and app banking matter more than the UK setup
- Vivid Money If cashback on card spend is the priority
Frequently Asked Questions
How much does a Tide business account cost?
Four tiers, with a free entry — though it allows only a handful of transfers a month. The paid tiers differ mainly in foreign spending, savings rate and transfer allowance. All of it requires a UK address or a UK-registered company.
Is Tide a bank, and is my money protected?
Tide states it plainly in its own small print: Tide is not a bank. It is an electronic money institution authorised by the FCA (reference 900843). The accounts themselves are provided by ClearBank, and deposits there are covered by the FSCS up to £120,000. The catch: some members hold e-money accounts provided by PrePay Technologies instead, which are not FSCS-covered — they are safeguarded, which protects you against PPT's insolvency but is not the deposit guarantee scheme. Check your sort code: 04-06-05 is ClearBank and FSCS-covered, 23-69-72 is PrePay and is not.
Is the free Tide plan actually free?
Yes, there is no monthly fee — but it caps you at five bank transfers a month, and international card payments carry a 2.75% FX fee. For a freelancer paying a handful of suppliers and spending in sterling, that is genuinely free. Pay six suppliers a month, or spend abroad regularly, and the Free plan stops being the cheapest option rather than becoming expensive.
When is a paid plan worth it?
At two points. First, transfers: once the free allowance runs out, a paid tier costs less than the per-transfer fees. Second, spending abroad — the FX surcharge disappears on paid plans. Anyone holding a cash balance also gets a higher savings rate.
Can I open a Tide account from outside the UK?
Only with a UK company. Tide requires a UK residential address and phone number; applicants based elsewhere may apply as long as they are directors of a company registered with UK Companies House, and additional checks may follow. There is no German IBAN and no euro business account — for a freelancer based in Germany without a UK entity, this is not an option.
Verdict
Tide earns its place as a first business account for UK freelancers: no monthly fee, no hard credit check, open from the app the same day, and a strong Trustpilot record across tens of thousands of reviews. Two things to be clear about before opening one. The free plan's real limit is a handful of transfers a month, not its price — pass that and you are on a paid tier. And Tide is not a bank: the money sits with a partner bank and is FSCS-covered, unless your sort code falls under the safeguarded arrangement instead. Worth knowing which one you have before it matters.